 KI
The United States on the path to 2040
How far society, labour and the state have advanced in transition, calculated per capita.
The USA enters the economy that is coming as the leading AI power. On this page you can see where it stands on the way to 2040, measured with the same indicators as the other three countries, and how its 14 pillars are faring.
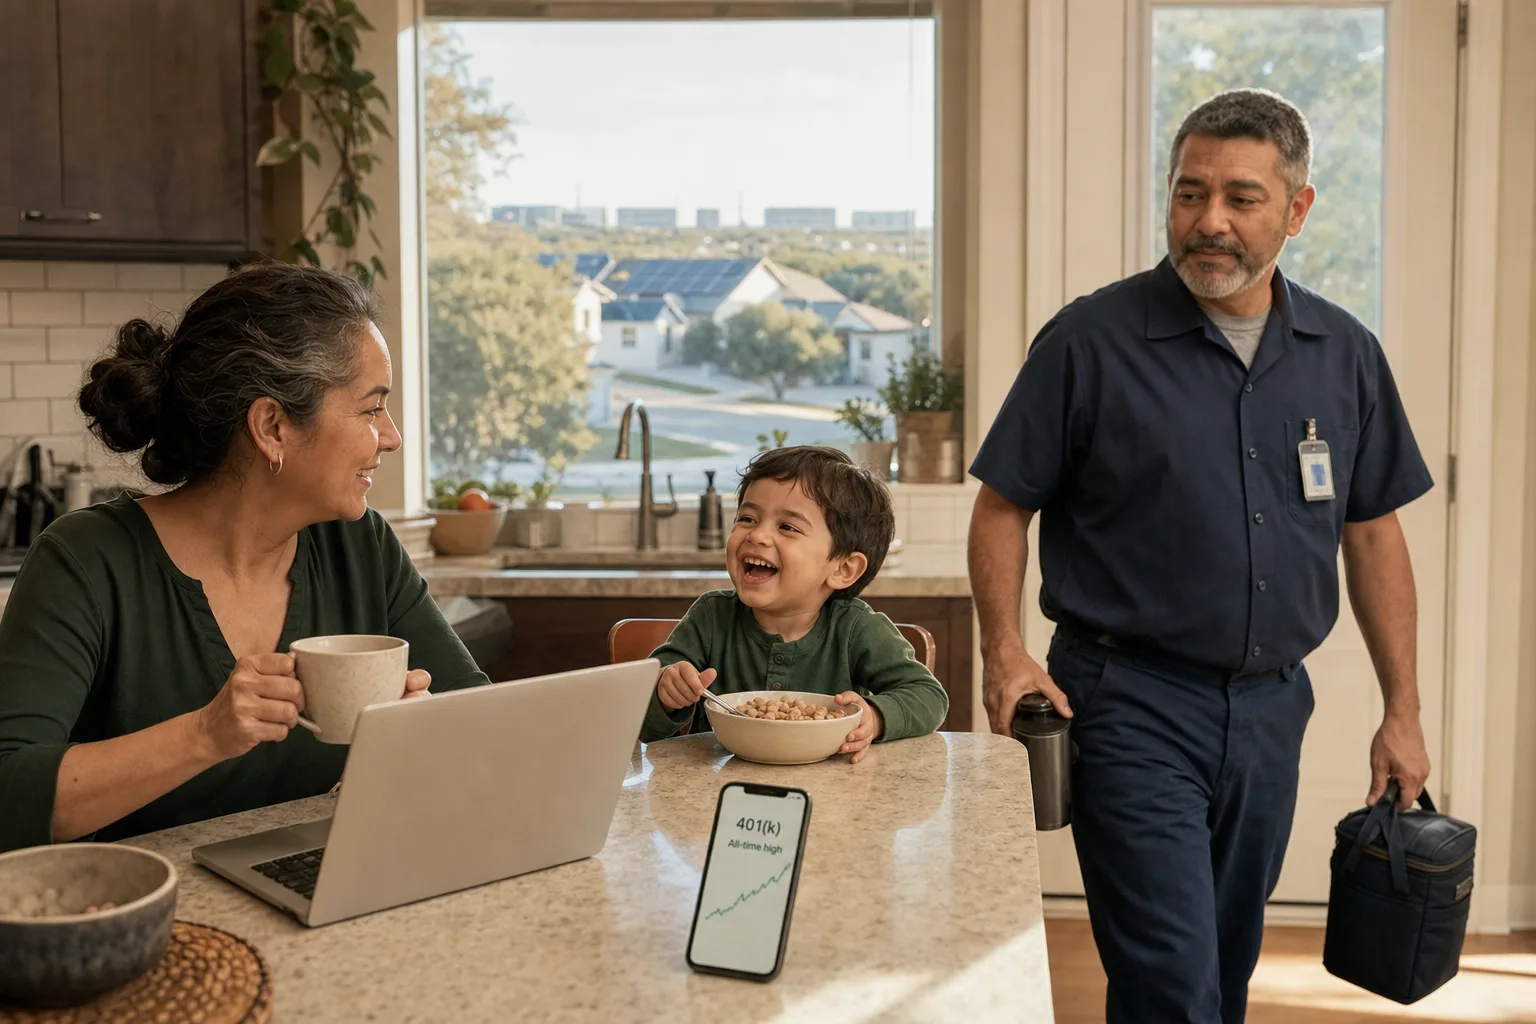
It is May 2040. A family from Austin, Texas, lives in an economy that has little in common with that of 2026. Paid employment is one of several forms of contribution. Yet unlike Europe, America organises change through the market: through funded capital, private insurance and equity ownership rather than redistribution and social partnership. The AI returns belong to the large technology companies. Through index funds and 401(k) accounts, a large share of households holds small stakes in them. Those who own assets gain; those who own nothing are left out. That tension defines the American path.
A day in the life of the Garcia family
Maria Garcia, 49, wakes up in a suburban house in north Austin. For fifteen years she worked as a paralegal at a law firm, specialising in contract review. When AI systems took over document review and research in the early 2030s, her team shrank from twelve to three. There was no redundancy process in the European sense, with short-time working and transition funds. Only a final pay cheque and three months' severance.
Today Maria works as an AI legal process auditor. She reviews the edge cases the model flags, takes responsibility for liability questions, and trains the systems with her professional expertise. She financed the transition herself, through an online certificate from a Texan university and a low-interest retraining loan. The flexible labour market found her a new position quickly, but offered no safety net had that not worked out.
Her husband Daniel, 51, is a technician maintaining climate-control and robotics installations. He services the cooling systems of the data centres that have sprung up around Austin. Texas has become a hub for computing capacity because of cheap energy. His work on physical machinery was harder to automate than Maria's desk-based role. Skilled manual work is more secure in this world than office work. AI has not brought him more time. The data centres run around the clock, and Daniel often works fifty hours a week on a shift rota, readily taking the overtime because it pays well. There is still no statutory right to paid holiday in the USA, as was also the case in 2026. The productivity of the new economy flows here into returns and wages, barely into free time.
A notification from the family's brokerage account appears on Maria's phone: their 401(k) has reached a new high. About forty per cent of it sits, as with almost all index savers, in a handful of large technology companies. The family thus owns a tiny stake in the very firms whose AI transformed Maria's former profession. Capital and displacement sit in the same account.
Their health insurance runs through Daniel's employer. During Maria's months of transition, the family had to fund cover themselves through the marketplace at considerable cost. The period without work was above all a period without reliable health protection. This link between employment and coverage shapes every life decision.
Their two adult children took different paths. Sofia, 27, develops AI software at one of the tech companies in Austin. Her brother Luis, 24, drove trucks between Dallas and Houston until driverless lorries took over the route. The first ran there in regular service as early as 2025. Today he monitors twenty vehicles simultaneously from a control centre, for less pay than he earned at the wheel. Both invest early in index funds. Where capital beats labour, ownership matters more than a salary.
Sofia has a son, Mateo, aged three. His nursery costs the young family almost as much as the rent. In 2024 the average in the USA was already around $13,100 a year. On two days when Maria works from home, she looks after him. Unpaid, as family care in America usually is.
In the evening Daniel reads about a state-level vote on incentives for new data centres. In Texas the outcome differs from California or New York. Federalism allows states to drift in very different directions. This is what a Wednesday in 2040 looks like: dynamic, full of opportunity, and without a safety net. We describe how this works as the Globalance Outlook.
How this world works
In 2040 the federal government still raises revenue primarily from income and payroll taxes; capital gains are taxed comparatively lightly. Unlike Europe, there is no data levy and no nationwide carbon pricing at federal level. Some states lead the way; others do not move at all. Rebuilding the tax system for the age of capital remains the great unresolved choice.
Income security remains tightly tied to paid work and asset ownership. Universal Basic Income (UBI) has never arrived. Instead, three sources carry the weight: wages from flexible work, capital income from 401(k) accounts and portfolios, and a thin state safety net as a last resort. Those who own capital have several foundations; those who do not have only one.
AI returns are concentrated among a handful of platform groups; the ten largest account for around 40% of stock-market value (S&P Dow Jones Indices). Through index funds, however, roughly half of all households hold small stakes in them. Ownership is both broadly spread and extremely concentrated. The top one per cent holds more equities than the bottom 90 per cent combined.
The labour market remains at will: flexible, fast, with no short-time working. Changing jobs and reinventing oneself are the norm, often several times in a lifetime. Gig and project work are widespread. This moves displaced workers quickly into new roles, but leaves them without a safety net during the transition. Working hours have barely fallen. Those with sought-after skills work more and earn more. Those who have been displaced often combine several jobs.
Elite universities and community colleges sit alongside unequal schools. Retraining runs on market terms through online certificates and bootcamps, often privately funded. Reskilling at 45 is normal. Access depends on income, and student debt limits social mobility.
The federal structure allows states to diverge sharply. Tax policy, AI regulation and social policy differ fundamentally between Texas, California and New York. Political polarisation makes bipartisan federal action difficult. Much is decided at the state and local level.
There is no federal data-protection standard comparable to EU levels; regulation favours innovation and leaves significant gaps. Foundation models are built by private companies with enormous computing power. This drives pace and global leadership, but raises serious questions about liability, safety and the concentration of power.
Retirement provision rests on two pillars: pay-as-you-go Social Security, whose trust fund is under pressure, and funded 401(k) plans. Healthcare remains predominantly private and employer-linked; Medicare covers the elderly. Care work is a fast-growing occupation, but poorly paid.
Childcare remains a private matter. Tax credits exist, but there is no legal entitlement to a place and no federally paid parental leave. Those with grandparents nearby have an advantage.
Data centres satisfy their energy appetite with abundant natural gas and growing renewables; electricity is comparatively cheap. Climate policy shifts with political majorities and varies widely by state. Growth and emissions decouple through technology, not through restraint.
The American ethos of achievement and self-realisation carries through the upheaval. Identity draws on entrepreneurship, reinvention, and ownership. The old question "What do you do for a living?" gives way to "What are you working on right now, and what do you have a stake in?"
What set the system in motion
This world did not emerge from a single decision. It is the result of a chain of triggers between 2027 and 2035.
a wave of automation in knowledge work and office roles. Law firms, banks, call centres, and software houses cut hundreds of thousands of well-paid positions that AI models could absorb. The flexible labour market accommodated the movement — quickly, but not without pain.
The AI and compute boom drove the market capitalisation of a small number of technology companies to unprecedented heights. Those invested through 401(k) plans benefited; those who owned nothing fell further behind. The debate over equity participation became the central distributional question.
Social Security was heading towards a funding gap in the early 2030s (SSA Trustees). Combined with high federal debt, this forced reforms. America leant more heavily on a funded system than on pay-as-you-go insurance.
With the federal government paralysed, the states took the initiative. Texas attracted data centres with cheap energy and low taxes; California and New York experimented with equity participation and social protection models. Federalism became a laboratory.
Competition with China for AI leadership made compute, chips and talent a national priority. Export controls and industrial policy (CHIPS Act) established the USA as the home of global compute, while reinforcing concentration among the large players.
What is robust about this story
We are not saying: this is exactly what will happen. We are saying: it could happen, if the right decisions are taken in time.
Three questions remain open: the pace (2040 is an assumption, not a promise), political cohesion (polarisation and federalism can push the path in several directions), and distribution (whether the gains from AI are shared broadly or concentrated further remains the great unknown). Whether the market will ever distribute the free time that machines create also remains to be seen.
The pillars of the United States
Whether the USA shapes the transformation or suffers it will be decided by its pillars, from public finance through education and labour to social cohesion. Each pillar shows where the country stands, where it is under strain, and which choices lie ahead. The badge at the top right shows the current status of that pillar in the USA:
On track: The pillar is moving in the right direction. Building up: The first building blocks are in place, but the pace must increase. Open turning point: The directional decision has not yet been taken. Critical turning point: This is where the scenario will be decided.
How far along is the USA?
The USA has the most AI computing power per capita and, of the four countries, spends the largest share of its economic output on research. Broadly, however, the country keeps pace less than the headlines suggest: roughly as many people use generative AI as in Germany, and AI publications per capita are no higher. Workers put in 36.3 hours a week, longer than in Europe, and only 43 per cent of electricity comes from low-carbon sources. This puts the USA in third place, just behind Germany.


The US dominates AI technology: computing power, leading models and private capital. Readiness 2040, by contrast, measures how far AI has already penetrated society and labour per capita.
Sources: Epoch AI, Stanford AI Index 2026, Borderstep/Bitkom, OpenAlex · As of 10 October 2026 · not included in the Readiness 2040 score · See full technology view →
How it is calculated
Each indicator receives 0 to 100 points. 0 is the starting level, 100 the 2040 vision, the same for all four countries. Within a group the points are averaged; Readiness 2040 is the average of the four groups. In the infrastructure group, low-carbon electricity and computing power count for half each. Distribution is shown but does not count.
The ten indicators
For context: distribution
We show how income and wealth are distributed for each country. This does not feed into Readiness 2040, because these figures mainly reflect a country's economic structure rather than how far its transition has progressed.
The global index measures alongside this how far the world economy as a whole has progressed on this path. Readiness 2040 is a distinct measurement with its own scale; the two figures cannot be compared directly.
14 measures, four countries
The lead source for each topic, USA highlighted. «–» means: no comparable measurement.
Microsoft AI Diffusion Report 2025 H2 · second half of 2025
Stanford AI Index 2026 · 2024
OECD Employment Outlook 2023 · 2019
OECD PIAAC 2023 (Trends in Adult Learning 2025) · 2023 (Erhebung 2022/23)
ILOSTAT (ILO) · 2022–2025
UBS Global Wealth Report 2026 · 2025
Show all 14 topics
OECD Pension Markets in Focus 2025 · 2024
Penn World Table 11.0 · 2023
IWF WEO April 2026 · 2025
Stanford AI Index 2026 / LinkedIn · 2025
Ipsos AI Monitor 2026 · 2026
OECD PIAAC 2023 · 2023
WVS/EVS Welle 7 (Erhebungen 2017–2018) · 2017–2022
WVS/EVS Welle 7 (Erhebungen 2017–2018) · 2017–2022
All values with primary sources: Country comparison as Excel
The seven areas: where the United States gains and where it comes under pressure
The seven areas of transformation through an American lens. Select an area on the left: the detailed metrics with country comparisons are shown on the right.
Technology & AI
The USA is the undisputed global AI power. It is home to the leading foundation models, the bulk of global computing power, and the world's deepest pool of venture capital. No other country combines talent, capital, and compute at comparable scale.
From OpenAI and Google DeepMind to Anthropic, the world's most capable models are built in the United States, supported by data centres that account for the lion's share of global AI compute (Stanford AI Index). Venture capital flowing into AI dwarfs every other region by a wide margin. China leads on AI patent volume, but the United States is clearly ahead on frontier models and their commercialisation. The risk is not falling behind — it is concentration: value creation is clustering among a handful of West Coast corporations.
 USA95China78Germany52
What is measured: share of globally leading foundation models and available AI computing power.
Source: Stanford AI Index
USA88China95Germany66What is measured: AI patent filings per million inhabitants; China leads on volume, the USA on quality.
Source: USPTO / WIPO
USA100China60Germany30What is measured: venture capital invested in AI start-ups per capita; the USA lead the world.
Source: Stanford AI Index / PitchBook
Assessments relative (0–100), compiled by the Globalance Research Team.
Economics & Capital
The United States combines high productivity, deep capital markets, and an economic structure weighted towards services and technology. Its stock-market capitalisation relative to GDP is the highest among large economies. Value creation shifted early towards software, data, and platforms.
At around $89,000 GDP per capita in purchasing-power terms (IMF) and a stock-market capitalisation well above 150% of GDP, the United States is the most capital-market-centred large country. About 3.5% of GDP flows into research and development (OECD), driven by the private technology sector. In the economy ahead, value creation is moving from physical production to intangible goods. There, America has a structural advantage. The other side is a marked concentration among a small number of platform groups.
USA95China45Germany80What is measured: Productivity measured as GDP per hour worked.
USA100China55Germany45What is measured: Depth of capital markets relative to economic output; the US leads by a clear margin.
Source: World Bank / SIFMA
USA95China80Germany82What is measured: Internal expenditure on research and development, approximately 3.5 per cent of GDP.
Source: OECD / NSF
Assessments relative (0–100), compiled by the Globalance Research Team.
Labour & Automation
A flexible labour market allows rapid reallocation, but the high share of cognitive office and knowledge work leaves the middle class particularly exposed. With limited social safety nets, the transition can unfold quickly — and harshly.
The U.S. BLS and the OECD show that well-paid office and knowledge occupations in particular, such as legal assistance, accounting, customer service, and programming, carry high automation potential. Unlike in Europe, there is little short-time work or social partnership to manage transitions. High job mobility can move displaced workers into new roles more quickly. Or it can leave them without a safety net. Whether AI strengthens or hollows out the middle class will be decided by retraining and access to capital income.
USA75China55Germany66What is measured: Share of workers with high AI automation potential (higher = greater pressure).
USA88China58Germany52What is measured: Speed of job transitions and reallocation of labour (higher = more flexible).
Source: U.S. BLS
USA35China45Germany82What is measured: Protection against job loss and transitions (higher = stronger); the US scores weakly.
Source: OECD
Assessments relative (0–100), compiled by the Globalance Research Team.
Monetary Policy & Finance
The US dollar remains the world's reserve currency, and the capital markets are unmatched in depth. Yet high public debt narrows the fiscal room to manoeuvre. Broad equity ownership anchors participation, though it is distributed very unequally.
Federal debt stands above 120% of GDP and the interest burden is rising (IMF / CBO). That sits in contrast to the global dominance of the dollar and US capital markets. About 62% of Americans own equities (Gallup 2025), mostly through 401(k) plans. That creates broader participation in capital than in Europe. Yet the distribution is extremely skewed: the top 1% holds more equity wealth than the bottom 90% combined. Capital depth and inequality are two sides of the same coin.
USA30China55Germany62What is measured: Lower = more room to manoeuvre; bar shows fiscal headroom (US debt above 120 per cent).
USA90China30Germany38What is measured: Share of the population holding equities or funds, approximately 62 per cent.
Source: Gallup / Federal Reserve
USA100China50Germany55What is measured: Size and liquidity of capital markets relative to the economy.
Source: SIFMA / World Bank
Assessments relative (0–100), compiled by the Globalance Research Team.
Geopolitics & Governance
The United States controls the key technologies of AI, from chip design through foundation models to cloud infrastructure, and sets global standards through export controls. Political polarisation and uncertainty over alliances are the weak point, not technological dependence.
Through companies such as Nvidia, the major cloud providers and the leading AI laboratories, the United States commands a sovereignty in AI hardware and models that other nations are striving to match. Export controls on advanced chips have become a geopolitical instrument. The more acute vulnerability is domestic: deep polarisation, shifting foreign policy and a federalism that is allowing states to drift apart. The manufacture of cutting-edge chips also remains heavily dependent on Taiwan.
USA100China80Germany50What is measured: Control over compute, foundation models and AI talent in a global comparison.
Source: Stanford AI Index
USA82China65Germany46What is measured: Control over chip design and manufacturing supply chains (design strong; fabrication dependent on Taiwan).
Source: SIA / BIS
USA55China60Germany78What is measured: Political predictability and institutional stability (higher = more stable).
Source: World Bank Governance Indicators
Assessments relative (0–100), compiled by the Globalance Research Team.
Society & Psychology
America is open to innovation and technologically engaged, yet struggles with high inequality, declining institutional trust and deep political polarisation. Social cohesion is the greatest unknown on the American path.
The population is more open to new technology than many European societies. That is an advantage for AI adoption. At the same time, trust in government, media and institutions is low (Edelman Trust Barometer), and wealth inequality ranks among the highest in the industrialised world. Political camps face each other with no room for compromise. If AI concentrates gains further upward, social division risks deepening rather than closing.
USA40China70Germany50What is measured: public trust in state institutions.
Source: Edelman Trust Barometer
USA30China45Germany60What is measured: Evenness of wealth distribution (higher = more equal); the US is highly unequal.
Source: Federal Reserve / OECD
USA66China78Germany46What is measured: Openness of the population to AI in everyday life and the workplace.
Source: Pew Research
Assessments relative (0–100), compiled by the Globalance Research Team.
Investment Implications
Through 401(k) plans and index funds, American households participate broadly in the productive capital stock of the new economy, far more so than European savers. The advantage is real, but highly unequally distributed and heavily concentrated in a handful of technology stocks.
Funded pension assets per capita rank among the highest in the world thanks to 401(k) plans and IRAs (OECD). In an economy where returns on capital outpace labour income, broad equity ownership gives the United States a structural participation advantage. Yet the concentration is twofold: wealth sits predominantly with upper-income groups, and the index funds themselves have roughly 40 per cent of their holdings in a handful of Big Tech companies. Those who own nothing remain on the outside.
USA95China40Germany42What is measured: Funded pension assets per capita (high in the US, driven by 401(k) plans).
Source: OECD / Federal Reserve
USA90China35Germany38What is measured: Prevalence of equity and fund ownership in the population, approximately 62 per cent.
Source: Gallup / Federal Reserve
USA80China60Germany42What is measured: the share of forward-looking, productive investments within portfolios.
Source: Globalance perspective
Assessments relative (0–100), compiled by the Globalance Research Team.
What to do in the USA
Concrete steps on three levels, ordered by who decides: you as an investor, companies and institutions, and policymakers.